Embedded payments are becoming a strategic priority, but most UK businesses are still some distance from a truly connected experience.
Businesses increasingly expect financial capabilities to form a natural part of the platforms they use every day. Payments, payouts, reconciliation, reporting and account functionality are no longer viewed as isolated back-office services. They influence the overall user journey, the efficiency of operations and, ultimately, business performance.
Software and financial services providers recognise the opportunity. Embedded payment solutions can reduce friction, deepen customer relationships and create new revenue streams. Yet despite growing investment and enthusiasm, only 10.8% of UK businesses using embedded payments and payouts describe their experience as fully integrated.
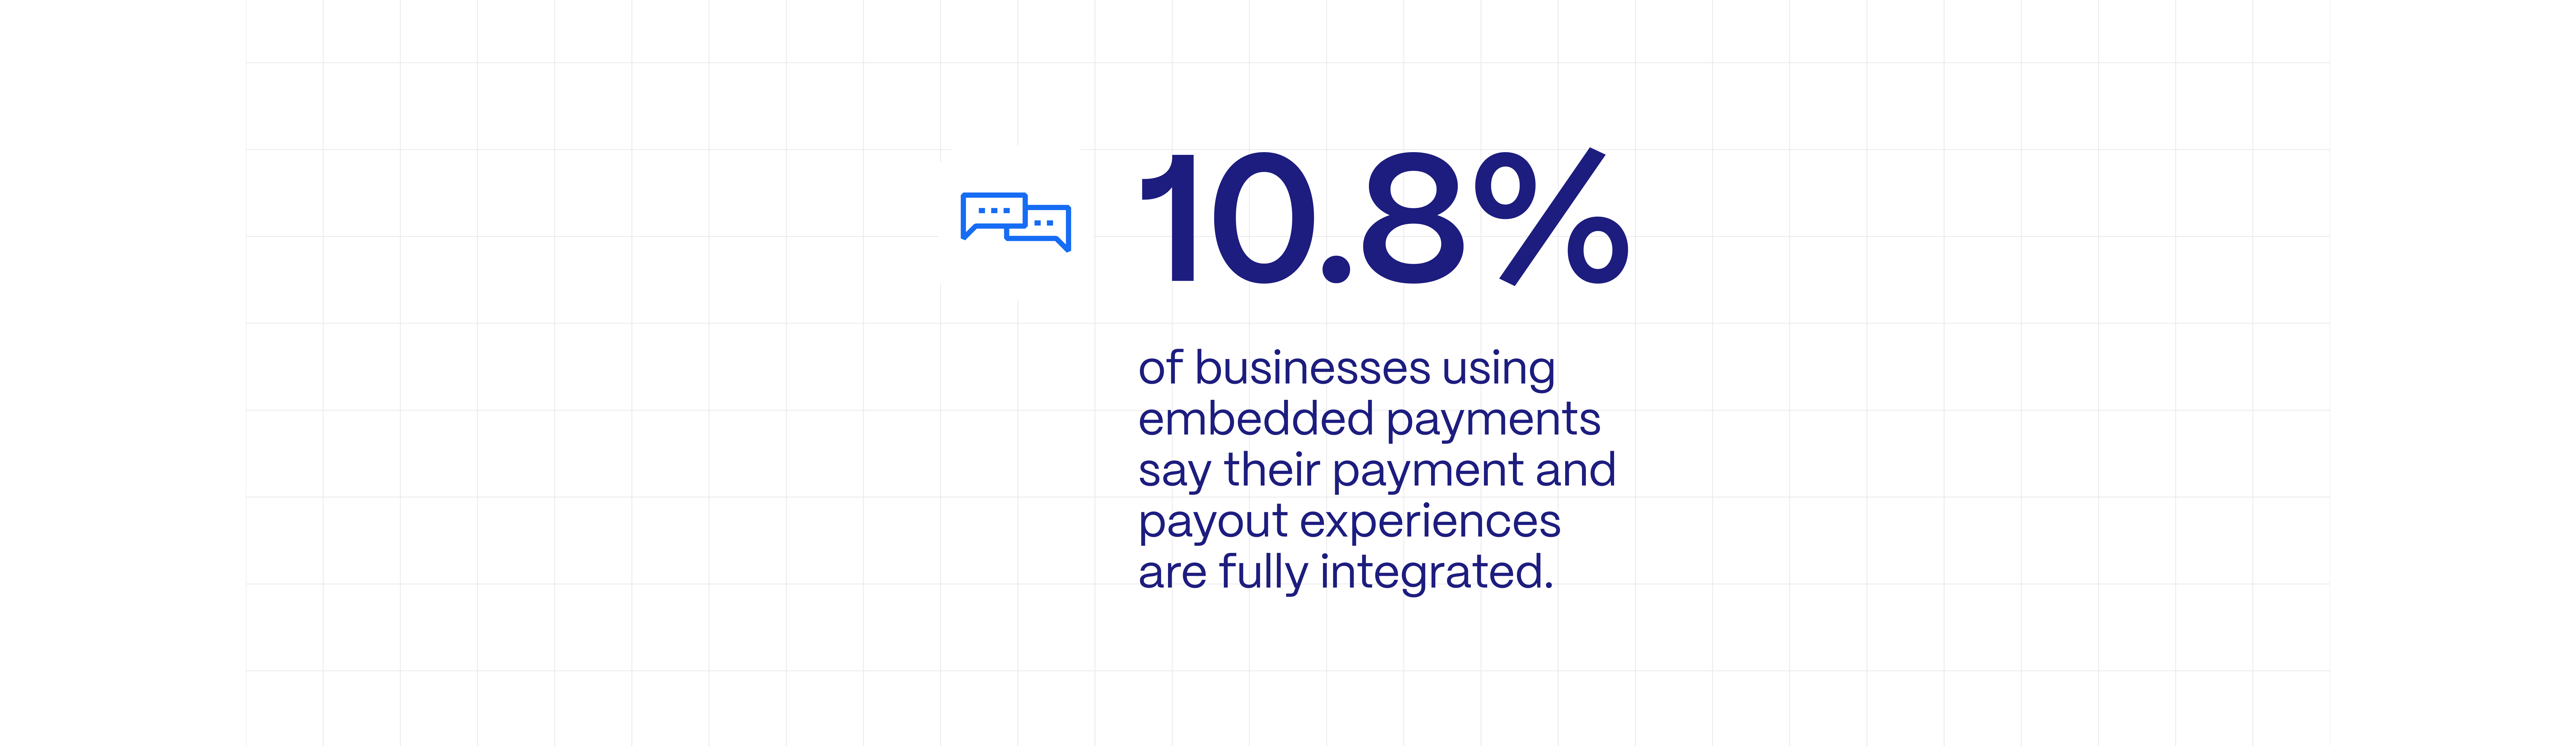
This is the embedded payments reality gap: a disconnect between making financial capabilities available and making the entire experience feel connected.
Closing that gap will require providers to think beyond the payment transaction.
In this article, we explore what will define the next phase of embedded finance and how B2B platforms and software provides can successfully connect payments with the workflows, systems and information surrounding them.
The promise and benefits of integrated payment products
Integrated payments bring financial capabilities directly into the software environments where users already work.
For a business user, that could mean paying a supplier from within an accounting platform, receiving funds through a specialised SaaS solution or managing an e-money account without moving between separate portals and banking solutions. The financial service becomes part of the task the user is trying to complete, rather than an additional process they must navigate.
For B2B platforms, fintechs and software providers, the potential benefits of embedded payments include:
- Reducing friction across user journeys
- Improving retention through a more cohesive experience
- Creating new and recurring revenue streams
- Increasing platform stickiness
- Differentiating the product in a competitive market
- Gaining deeper insight into how users operate
The strategic significance of these capabilities is already widely understood. Three quarters of businesses surveyed for our embedded payments research conducted by IDC recognise their strategic value.
But the software and financial services providers realising the greatest value are not simply adding payment functionality. They are designing around the broader business outcome.
A business user wants to pay a supplier, collect revenue, reconcile a transaction or understand their cash position. The experience is successful when the financial capability helps them achieve that outcome with less effort.
Why the operational reality of embedded payment experiences still falls short
The payment itself is often only one step in a much broader operational journey.
A transaction may be initiated through one platform, processed by another provider, monitored through a banking portal and later reconciled in an accounting system. Each component may work as intended, but the overall experience can still feel fragmented.
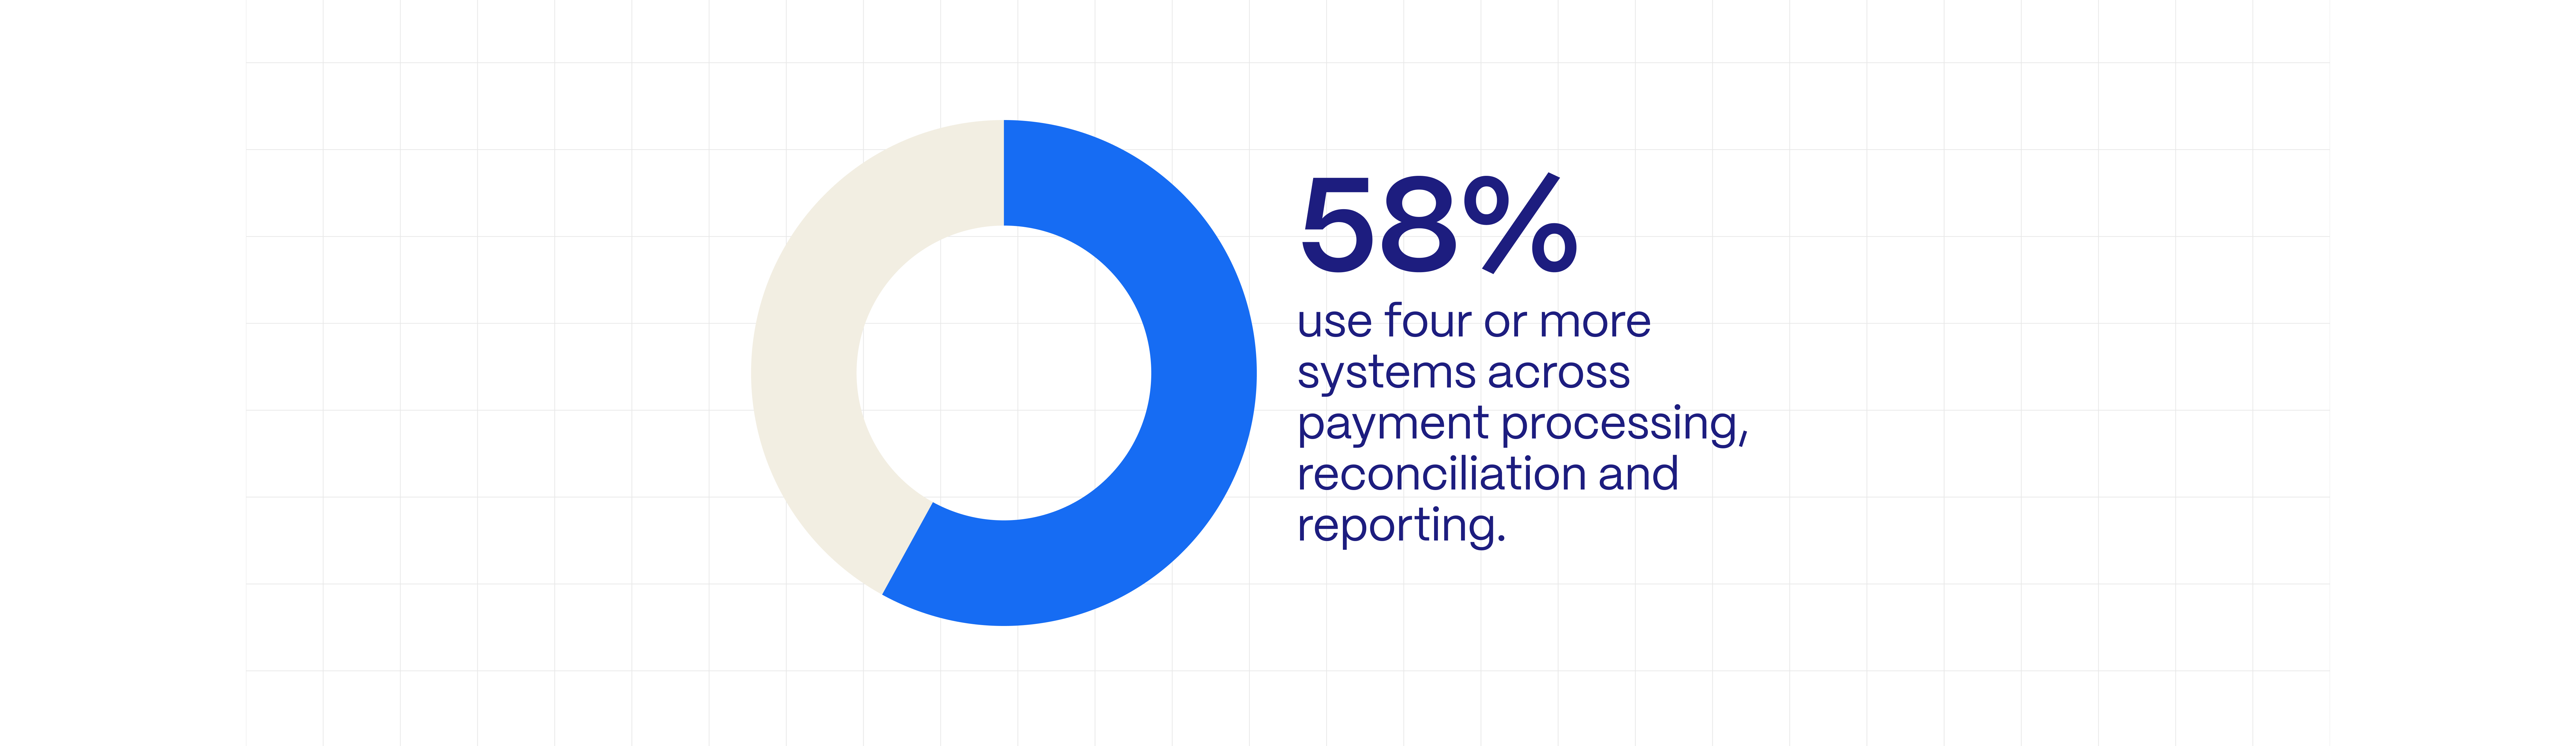
In fact, more than 58% of the UK organisations surveyed use four or more systems across payment processing, reconciliation and reporting.
Several underlying barriers contribute to this fragmentation.
Legacy systems make connected experiences harder to deliver
Many businesses operate with established infrastructure that was not designed for real-time data exchange or API-led embedded financial experiences.
Connecting modern embedded online payment solutions with legacy systems can require additional development, middleware and manual processes. Even when integration is technically possible, the resulting experience may not provide the speed, visibility or consistency businesses expect.
Fragmented technology and tools create fragmented workflows
Adding another product to an already complex technology stack does not necessarily simplify the user experience.
Payment processing, accounting, payroll, banking, tax management, expense management and reporting may all sit in separate systems. As explored in this analysis of why managing business finances remains unnecessarily difficult, individually effective products can collectively create significant operational complexity.
The more frequently users must transfer information, switch interfaces or verify data manually, the more visible that complexity becomes.
Vrush Sumanoharan
Product Marketing Manager
Edenred Payment Solutions
Organisational silos can undermine technical integration
Delivering integrated payments is not solely an engineering challenge.
Product teams may focus on the user interface, finance teams on reconciliation and commercial performance, and engineering teams on technical resilience. Risk and compliance teams will have their own requirements. If these priorities are addressed separately, the resulting payment journey can mirror those internal divisions.
A technically sound embedded payment solution can therefore still feel disconnected if no team owns the end-to-end experience.
Security and compliance requirements add complexity
Payments and payouts must operate within demanding security, regulatory and compliance frameworks.
These safeguards are essential, but they can create additional steps across onboarding, authentication, transaction monitoring and reporting. The challenge is not to remove necessary controls. It is to design them into the business workflows, so they protect users without making the experience feel cumbersome.
Limited internal resources encourage short-term integration decisions
Building embedded payment capabilities involves more than connecting an API.
Software and financial services providers need the right product, engineering, compliance, operational and customer-service expertise. When resources are constrained, teams may focus first on launching the core capability, with optimisation of the wider journey deferred to a later stage.
That can create an experience that is technically embedded but operationally incomplete.
Why technical integration alone is not enough for embedded payments
The presence of a payment capability does not automatically create an integrated payment experience.
Businesses delivering integrated payment solutions often define success in technical terms: the API is connected, the transaction can be initiated, and the funds move as expected. Business users define success differently. They experience every payment-related activity as part of one workflow.
From their perspective, integrated payments should be:
- Invisible: The payment capability sits naturally within the task being completed.
- Frictionless: Users encounter fewer unnecessary steps, handovers and manual interventions.
- Contextual: The right capability appears at the right point in the workflow.
- Secure: Controls protect users without introducing disproportionate complexity.
- Consistent: Information and functionality remain connected across systems and channels.
- Transparent: Users can see transaction status, access relevant data and understand what happens next.
Visibility is particularly important. 67% of UK businesses responding to the IDC research identified a lack of data transparency and transaction status updates as a shortfall in their payout experience.
This shows why speed alone is not enough. A fast transaction can still create operational friction if users cannot easily confirm its status, investigate an issue or reconcile it with the relevant record.
The real challenge is embedding payment solutions so seamlessly that they become part of the natural user experience and business workflow.
How software and financial services providers can solve the operational challenges of embedded payments
Successful integrated payment solutions are designed around the full financial workflow rather than an individual product feature.
Four characteristics can help software and financial services providers deliver a more complete experience for business users.
1. Begin with a clearly defined user outcome
Leading providers start by identifying the process they want to improve.
That might be helping an SME pay suppliers more efficiently, enabling a marketplace to distribute funds or allowing an accounting software user to reconcile transactions automatically.
Beginning with the outcome helps teams determine which capabilities, data and integrations are genuinely required. It also prevents the embedded payment product from becoming a standalone feature without a clear role in the user journey.
2. Connect embedded payment capabilities with business workflows
A payment becomes more valuable when it is connected to the systems and activities around it.
For example, integrating payments with invoicing, reconciliation, reporting and account functionality can remove several manual handovers from a single process. The user benefits from one connected journey rather than a collection of adjacent products.
This shift from embedding financial products to connecting financial workflows is explored further in the guide to embedded payment products for accounting software providers.
3. Prioritise data visibility, transparency and control
The best embedded payment solutions help users understand what is happening before, during and after a transaction.
Clear status information, accessible transaction data, reliable reporting and exception-management tools enable businesses to act with greater confidence. They also reduce the time teams spend moving between systems or contacting different providers for answers.
Visibility should therefore be treated as part of the product experience, not as an additional reporting feature.
4. Build for long-term adaptability
Business requirements, user expectations and regulatory obligations will continue to evolve.
Successful integrated payment solutions are supported by infrastructure and partnerships that can adapt over time. This includes APIs that enable interoperability, scalable account and payment capabilities, consistent compliance support and access to the expertise required to develop new use cases.
Choosing the right embedded finance provider is therefore not only a technical decision. It is a longer-term product and operating-model decision.
The embedded payments market offers a significant opportunity for software and financial services providers
The fact that only 10.8% of UK businesses have achieved fully integrated payment and payout experiences should not be interpreted as evidence that embedded payments have failed.
It shows that the market has completed only part of the journey.
Access to embedded financial capabilities has expanded significantly. Software providers can now integrate payments, cards and e-money account functionality without becoming financial institutions themselves. But access to capabilities is no longer the principal differentiator. The next opportunity lies in making those capabilities easier to use, manage and connect.
For B2B platforms, fintechs, accounting software and vertical SaaS providers, closing the embedded payments operational gap can create tangible advantages: greater user retention, new revenue opportunities and a stronger competitive position.
As Rehana Mitha explores in her executive perspective on embedded payments, the most successful software and financial services providers may not be those with the longest feature lists. They will be those that remove the most operational friction.
The focus must be on how effectively integrated payments can become part of simpler, more connected business workflows.
Key takeaways about integrated payment experiences:
- Embedded payment capabilities are increasingly strategic, but only 10.8% of UK businesses currently describe their payment and payout experience as fully integrated.
- The greatest source of friction often sits across data visibility and transparency and disconnected systems.
- A technical integration is only the starting point. Users expect a seamless, contextual and transparent workflow.
- Leading software and financial services providers design around business outcomes, connect the wider financial journey, prioritise visibility and build for long-term adaptability.
- The gap between the promise of embedded payment products and the current operational reality represents a significant opportunity for software and financial services providers.
Embedded payments insights in 2026
Discover what UK businesses expect from embedded payment experiences and the opportunities for software and financial services providers.
Follow Edenred Payment Solutions on Linkedin
Stay up to date with the latest news and learn more about what we do